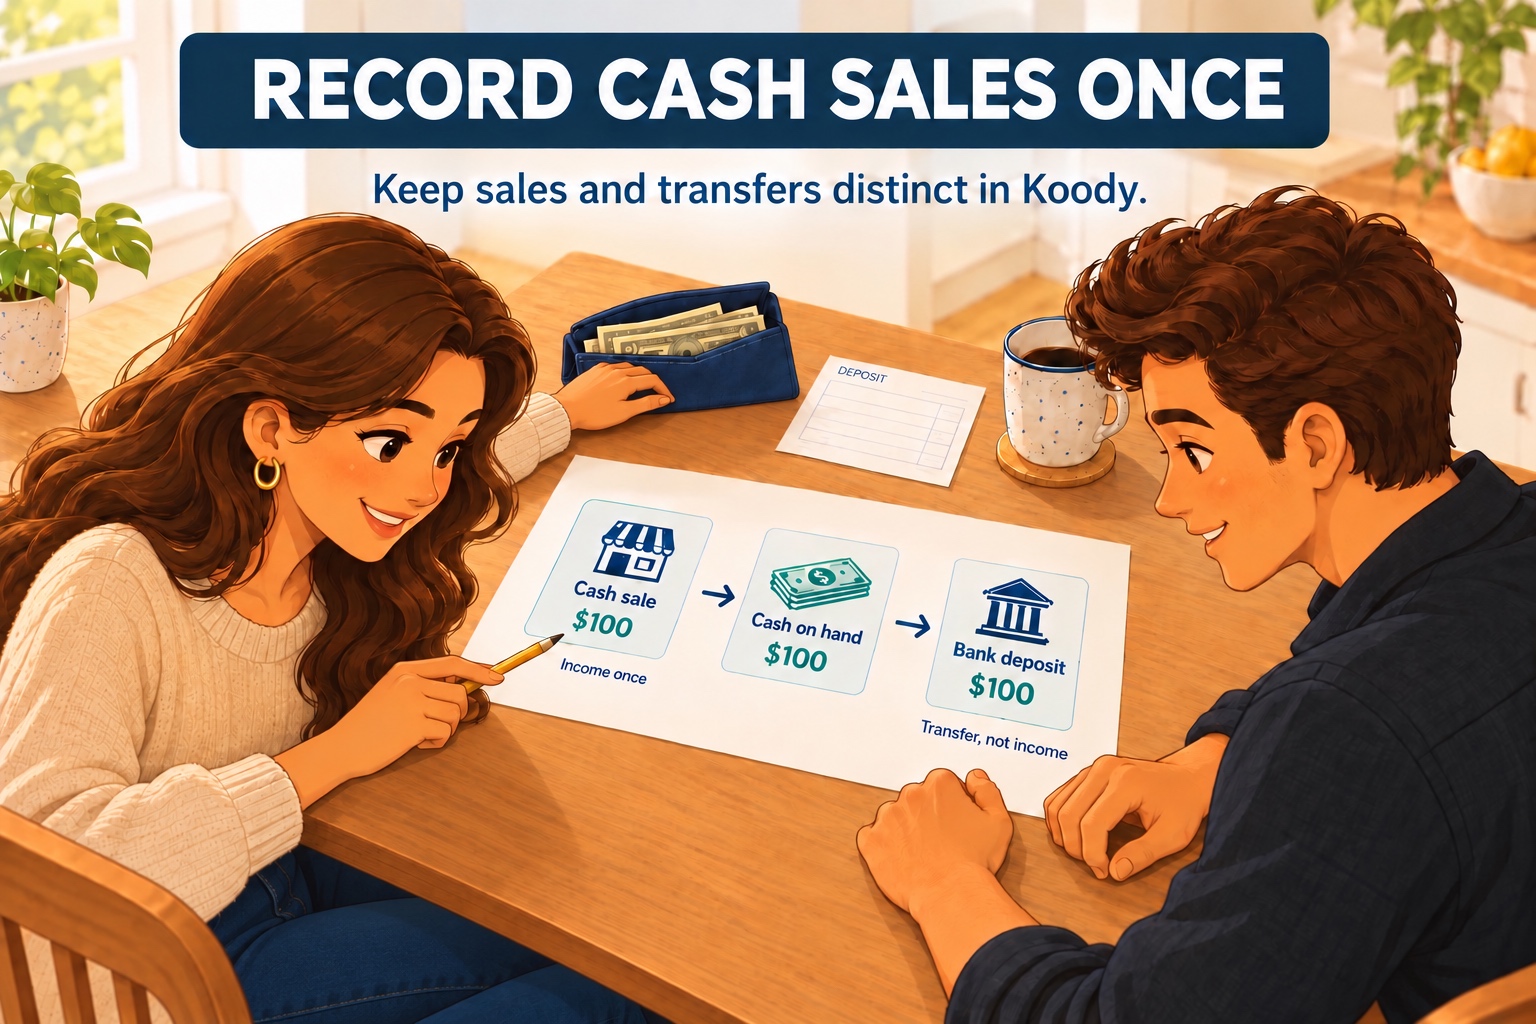
Record the cash sale when you receive payment
Suppose customers pay you $500 in cash for completed jobs on Saturday. On Monday, you deposit $400 and keep $100 for change. Assume no opening cash, sales tax, or refunds, and no cash expenses through Monday.
Your sales income is $500. Recording only the bank deposit would miss the $100 you kept. Recording both the cash receipts and the deposit as income would inflate sales to $900.
In Koody, add a Cash bank and a cash account in Business. Record the $500 there with Type set to Income and the appropriate Business category. Use the payment date, amount, and a description of the work. Keep the receipt or sales record with the entry.
Make the cash record while you can still identify the payments. A barber can use numbered receipts or an appointment list marked paid in cash. A driver can keep a dated list of cash fares. Record the amount you earned after giving change, not the value of the notes the customer handed over.
You can keep individual payment records or a daily total backed by a sales log. Choose one level of entry: adding the daily total on top of the individual payments would duplicate the same sales. Keep card payments separate from the cash total.
Individual entries help when you need to find a particular customer's payment. A daily total reduces the number of entries when you take many small payments. Before entering that total, add up the day's cash records and check whether any payments are already in Koody. Keep the detailed list even when you enter only its total.
Record the deposit as a transfer
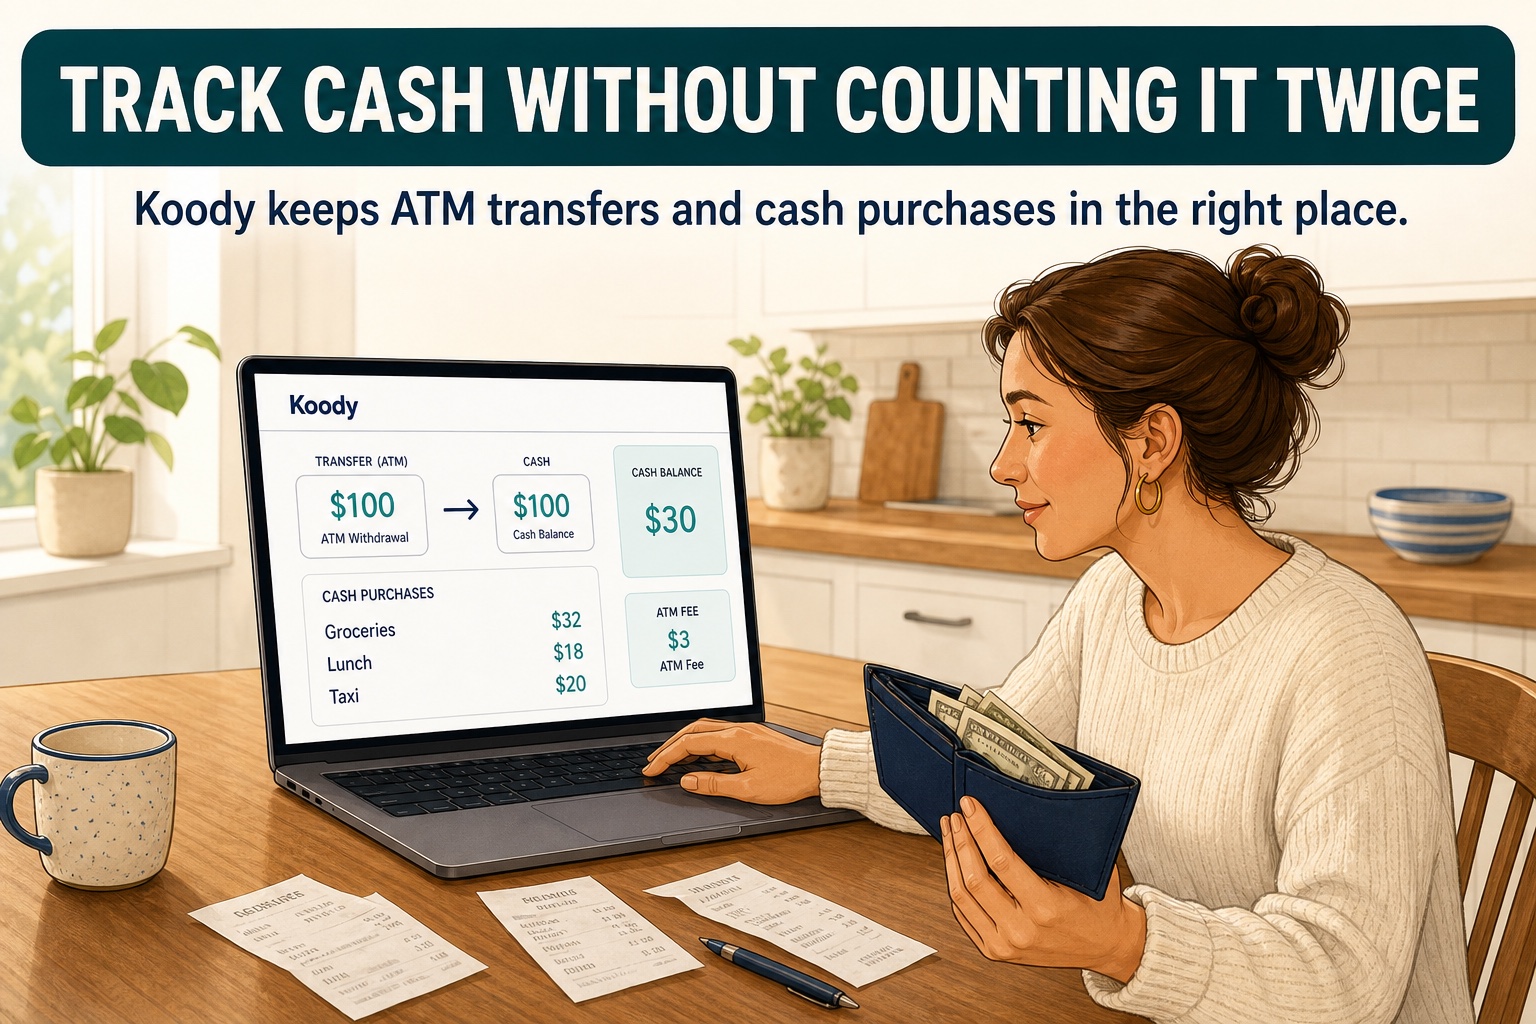
On Monday, use Koody's account transfer control to move $400 from your cash account to business checking. That creates the outgoing and incoming sides of the movement. Do not add another income entry for the deposit.
- Cash account: $500 received, less $400 transferred, leaving $100.
- Checking account: $400 received from the cash account.
- Sales income: still $500.
Use the deposit date for the transfer and retain the bank's deposit receipt. A note such as "Saturday cash takings; $100 retained for change" explains why the deposit is smaller than the sales total.
Saturday's sales stay dated Saturday even though the bank receives the cash on Monday. If those days fall in different months, the sales record and bank deposit will appear in different months too. Moving the sales date to make it match the statement would hide when customers actually paid you.
When one deposit contains cash collected over several days, note which daily records it covers. When you bank one day's takings in several trips, record each actual deposit separately. The cash account should show the amount still waiting to be deposited after each trip, rather than assuming every sale reaches the bank immediately.
Check the deposit when you import a statement
When you import your bank statement, check the $400 deposit against the transfer you entered. There should be one $400 incoming transfer in checking and one $400 outgoing transfer in cash. If the import adds the same deposit again, compare the records. Keep the linked transfer and remove only the confirmed duplicate imported deposit. Deleting the linked transfer would also remove its cash-account entry. Statement imports are a paid feature.
Category describes what a transaction is for; Type distinguishes Income from Transfer. Do not rely on renaming the deposit "cash transfer" while leaving its Type as Income.
Compare the amount, destination account, and deposit receipt before deciding that two entries are duplicates. A bank posting date can differ from the date you took the cash in. Two deposits for the same amount on different days may both be genuine, so the amount alone is not enough to identify a duplicate.
Count the cash still on hand
Count the retained $100 and compare it with your cash-account balance. Keeping it for change does not reduce sales. If you later spend some on business supplies, record that purchase separately as an expense from cash and retain its receipt.
For example, on Tuesday you use $30 of that retained cash for supplies. Record the $30 purchase on Tuesday. You now have $70 in cash and the $400 deposited on Monday, with $30 spent. Saturday's sales are still $500. Reducing the sales entry to $470 would hide the purchase instead of recording it.
Carry the remaining $70 into the next day's cash count. It is opening cash, so do not enter it as another day's sales. Count money kept for change as well as money set aside for the next deposit. Both belong in the cash balance until they leave it.
A bank statement shows what reached the bank, so keep the sales log, deposit receipt, and cash count together. If the numbers differ, check for an omitted payment, cash purchase, or duplicate entry before changing your sales total.
Keep your own money separate from customer payments too. Money you put into the business from personal savings is an owner contribution, not a sale. Label its source and keep it out of the daily sales total. Likewise, money you take for personal spending is an owner withdrawal, not a supplies expense. Record where it went so the cash count still agrees.
Keep cash sales beside your bank records
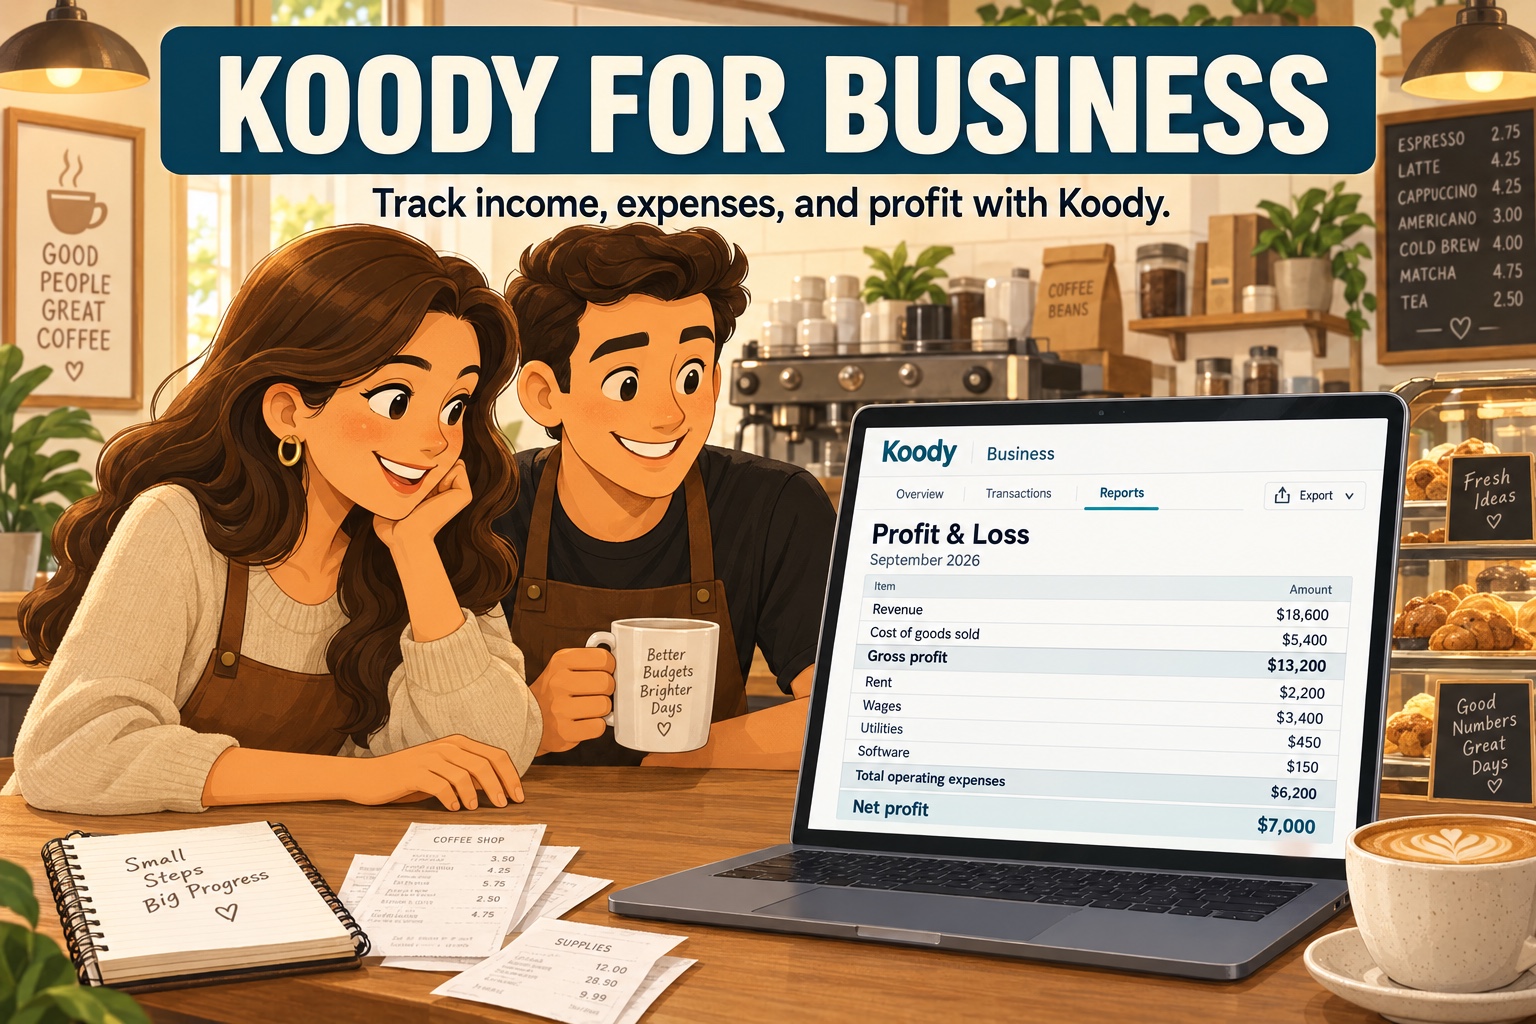
Record customer payments, transfer deposited cash, and keep supporting receipts in Koody. Review what you earned and where the money is now.
Track business income in KoodySources
General bookkeeping information. Sources accessed November 1, 2026.